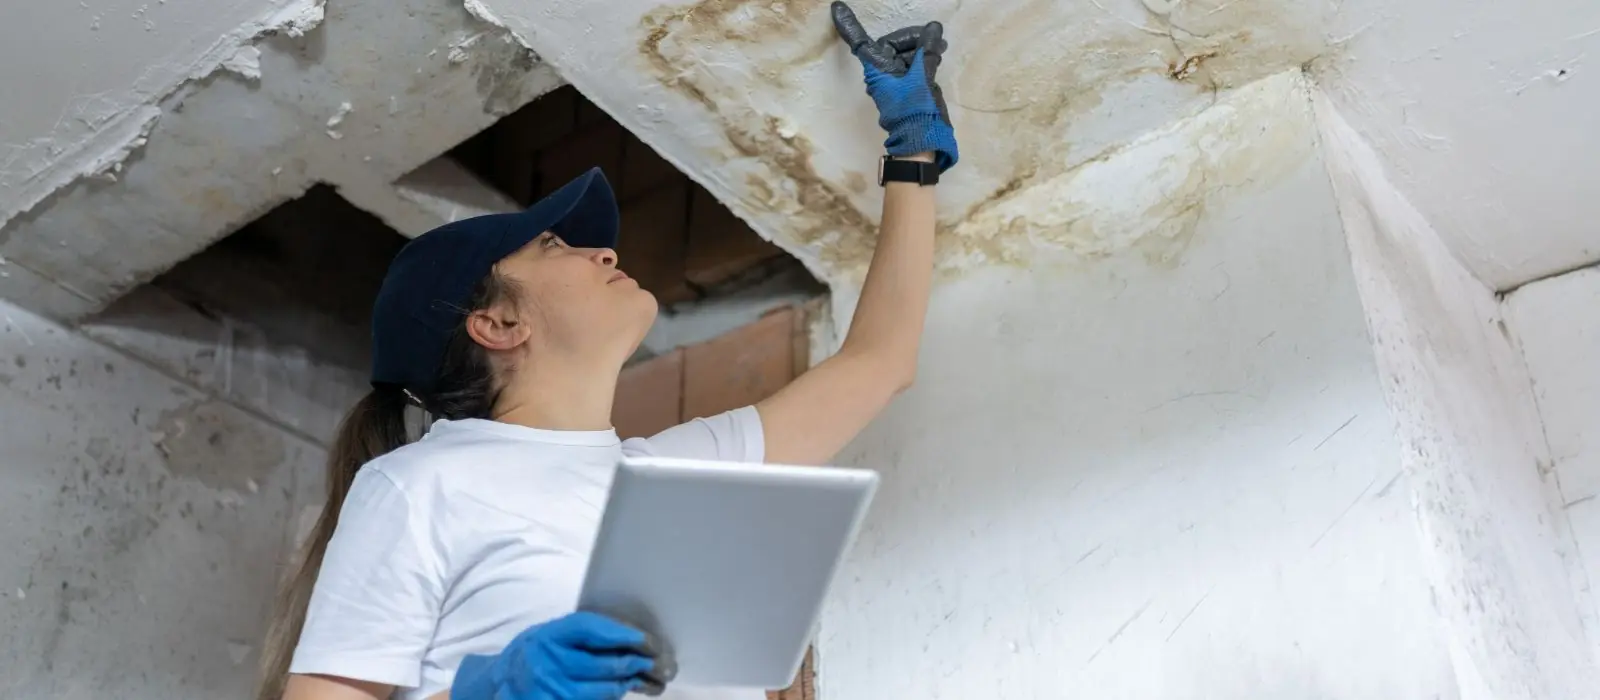
Homeowners policies are written around perils, meaning the specific causes of loss the policy names. Water damage is not one category. A pipe that bursts, a roof that leaks in a storm, a creek that rises into the yard and a sewer line that pushes waste up a floor drain are four different events with four different coverage answers.
Nothing below is a promise of coverage. Policies vary by company, by endorsement and by what is written on your declarations page, so use this as a map for the conversation with your insurer, not a verdict.
The sudden and accidental test
Most homeowners forms respond to water damage that is sudden and accidental. Think of a supply line that snaps, a water heater that ruptures or a dishwasher hose that lets go while you are at work. The event starts at a moment you could name, and the damage follows quickly.
The reverse is a loss that develops over time. A slow drip under a sink that rotted the cabinet over months, or a roof that wept into the attic for several seasons, is the kind of thing many policies treat as maintenance or wear and tear. The longer a leak could have been noticed and wasn't, the harder the claim conversation tends to be.
Flood versus water backup versus sewer backup
These three get confused, and the confusion is costly. Flood generally means water coming from outside the home across the ground, such as storm surge, overflowing waterways or heavy runoff. Water backup is water coming up through drains, sewers or a failed sump pump from inside the plumbing path.
Flood is typically excluded from a standard homeowners policy and requires separate flood insurance. Water backup and sump pump failure are often excluded too, but many companies sell an endorsement that adds limited coverage. The names and dollar limits vary, so read the endorsement list in your policy.
| Situation | Often covered? | What to ask your insurer |
|---|---|---|
| Burst pipe or snapped supply hose | Often yes, if sudden and accidental | Does it cover the repair of the pipe itself, or only the resulting damage? |
| Water heater or appliance rupture | Often yes for resulting damage | Is the failed appliance covered or only the damage it caused? |
| Slow leak under a sink or behind a wall | Often limited or excluded | How does the policy define long-term seepage and wear? |
| Roof leak in a windstorm | Depends on the cause | Does the policy require a storm-caused opening in the roof? |
| Storm surge or rising water from outside | Usually excluded from standard policy | Do I have a separate flood policy, and what is its waiting period? |
| Sump pump failure or drain backup | Only with an endorsement | Do I have a water backup or sump pump endorsement, and what is its limit? |
| Sewer line backup into the house | Only with an endorsement | Does the endorsement cover cleanup of contaminated water? |
| Condensation or ongoing humidity | Often excluded | Is mold covered and under what cause? |
Not sure what caused your water damage?
Call the dispatch line and describe what you see. Knowing the source helps you ask your insurer the right question.
Why the cause decides the answer
Your insurer will investigate the cause of loss, and the language of the policy is applied to that cause. That makes the first documentation job to identify the source clearly. Photograph the failed fitting or the entry point, and write down when you noticed it.
If the cause is unclear, say so. Do not guess at a cause on a phone call, because an offhand description can end up in the file as the official account.
Wear and tear, neglect and the maintenance exclusion
Policies commonly exclude damage from deterioration, rust, corrosion and lack of maintenance. A pinhole in an old copper line may be treated as wear, even though the resulting soaked ceiling feels like a sudden event. Insurers often separate the repair of the failing component from the damage it caused, and the second part may still be covered.
This is why dated photos of the failure matter, along with any plumber's report describing what failed and why.
What mold and drying costs look like to an insurer
Mold coverage is the part of a policy people read least. Many forms limit or exclude it, or cover it only when it follows a covered water event. Prompt drying after a covered loss is one of the things that tends to reduce the mold question later.
Our water damage repair page explains how repairs follow drying, and it is worth knowing the order of work before you talk to your adjuster.
Insurance note
This guide is general information, not insurance or legal advice. Coverage depends on your policy and the cause of the loss. Check your policy and ask your insurer before assuming a loss is covered or excluded, and do not wait on a coverage answer to stop water that is still spreading.
Marblehead note: flood coverage and checking your address
Mass.gov says standard homeowners and commercial business policies do not cover flood damage, and that you may have some coverage if your policy has an endorsement, also called a rider, for sump pump failure or water backup. It advises checking your declarations pages or asking your agent.
Marblehead's Engineering Department offers Flood Insurance Rate Maps (FIRM) through the town's flood insurance page, so you can look up your address before you decide on a separate flood policy. The practical step is to check the map for your street first, then ask your agent how a flood policy and a backup endorsement would each respond to your most likely loss.
Sources: Commonwealth of Massachusetts, mass.gov (Is your flood damage covered) and Town of Marblehead Engineering Department, marblehead.org
After a loss: protecting your position
- Stop the water and dry the structure promptly, since delay can turn a covered event into a larger and more disputed one.
- Report the loss to your insurer and ask directly which coverage you believe applies.
- Keep photos, plumber reports, drying logs and invoices in a single folder.
- Ask for any denial or partial payment in writing, with the policy section it relies on.
- If water came from outside, ask about flood damage restoration scope and whether your flood policy has a claim process separate from your homeowners policy.
Crews work across Salem and Beverly as well, so if you own more than one property on the North Shore you can ask about each.
What shapes the cost of a covered or uncovered loss
Source of the water
Clean supply water, storm water and sewage each carry different handling and disposal needs.
Materials affected
Drywall, flooring, insulation and cabinetry have very different salvage outcomes.
Speed of response
Water that sits longer spreads further and may add mold to the scope.
Policy deductible and limits
What you pay out of pocket depends on your deductible and any sublimits.
Scope and price are explained before work starts. Only an on-site look at the affected rooms gives a figure that fits your property, so call the dispatch line.
Frequently Asked Questions
Does homeowners insurance cover water damage from a burst pipe?
Often yes, because a burst pipe is usually a sudden and accidental event. Coverage for the resulting damage can differ from coverage for the pipe itself, so ask how your policy treats each.
Does insurance cover flood damage?
Mass.gov says standard homeowners policies do not cover flood damage. Flood coverage is typically a separate policy, and some flood policies have a waiting period before they take effect.
What is the difference between flood and water backup?
Flood is generally water entering from outside the home across the ground. Water backup is water coming up through drains, sewers or a failed sump pump. They are usually covered, if at all, by different policies or endorsements.
Is a slow leak covered?
Often not, or only in part. Many policies exclude long-term seepage and wear, though sudden damage that results from a failed component may still be addressed. Your policy wording controls.
How can I check whether my Marblehead address is mapped in a flood zone?
The town Engineering Department offers FIRM flood maps, and the town's flood insurance page lists the panels that apply to different parts of Marblehead. Ask your insurance agent how the map result affects your coverage options.
Will my insurer pay for water removal and drying?
If the cause is covered, reasonable emergency mitigation is often part of the claim, but this depends on your policy. Ask before work starts, and keep invoices and logs.